
When the first U.S. spot Bitcoin ETFs launched in January 2024, many observers declared that crypto had finally gone institutional. Capital flooded in, headlines followed, and the moment felt decisive.
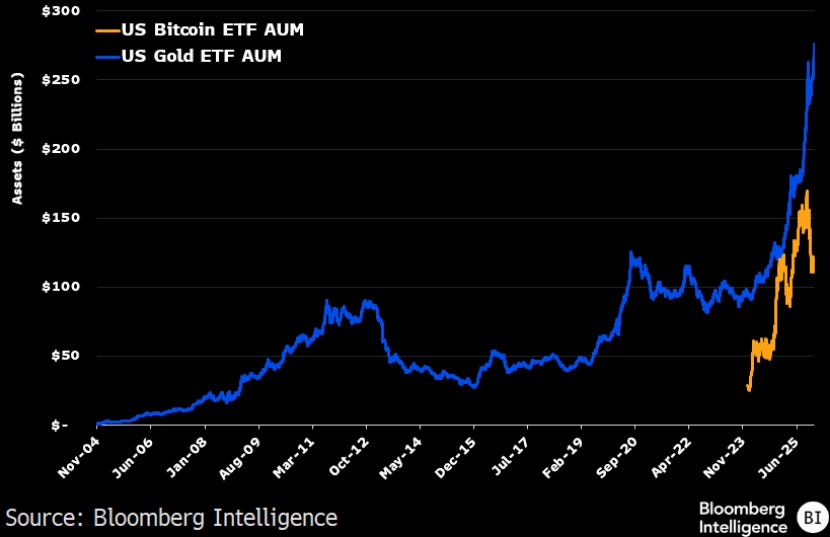
But in hindsight, that milestone was less a finish line than an on-ramp. ETFs gave institutions permission to own crypto. They did not yet allow institutions to use it.
That distinction matters. As Zach Pandl of Grayscale argues, the real institutional era begins when crypto starts integrating into the financial system itself—not just portfolios, but capital formation, settlement, payments, and balance sheets. By that standard, 2026 looks like a turning point.
The catalyst is regulatory clarity. For more than a decade, crypto innovation moved faster than the rules governing it. That ambiguity discouraged large pools of capital and constrained builders who needed to know the legal ground they were standing on. Grayscale’s successful challenge to the SEC helped open the ETF door, but the deeper shift now underway is from regulation by enforcement to regulation by framework. Market-structure legislation—still imperfect and unfinished—begins to define what crypto assets are, how they’re issued, and how they fit inside existing financial law.
This raises an obvious question. If crypto has been able to move value globally, nearly instantaneously, and at near-zero cost for more than a decade, why hasn’t it already taken over the financial world?
The answer is not technological. It’s institutional.
For most of its history, crypto lacked the legal, regulatory, and compliance scaffolding required to support large-scale economic activity. It worked brilliantly at the edges—peer-to-peer transfers, speculative trading, niche use cases—but couldn’t safely plug into corporate finance, regulated markets, or systemically important institutions. Speed alone isn’t enough. Financial systems also require trust, accountability, disclosure, and predictable rules. In other words, crypto needed institutions before institutions could use crypto.
That gap is now closing.
Regulatory clarity doesn’t just unlock investors; it unlocks issuers. Pandl’s vision of the institutional era is not simply more Bitcoin in pension funds. It’s a world in which companies—startups and Fortune 500 firms alike—issue tokens alongside stocks and bonds as a normal part of their capital structure. Equity, debt, and programmable digital assets begin to coexist, with clear disclosure rules and investor protections. That’s not a speculative evolution. It’s a structural one.
At the heart of this transition is crypto’s original “zero-to-one” breakthrough: finance with fewer intermediaries. The functions don’t change—payments, lending, trading, settlement—but the infrastructure does. Transactions settle instantly instead of days later. Markets operate around the clock. Assets move across borders as easily as information. Each improvement may seem incremental, but together they represent meaningful productivity gains in a system where small efficiencies compound at scale.
As crypto moves deeper into institutional finance, one theme becomes unavoidable: privacy. Retail users may tolerate transparency; institutions cannot. Corporations cannot expose payrolls, supplier payments, or treasury movements on public ledgers. Even at the individual level, financial privacy is a baseline expectation. As blockchain systems integrate with traditional finance—and as AI becomes better at pattern recognition—privacy shifts from philosophical preference to functional necessity.
Zach pointed to Zcash as a concrete example of how privacy can be implemented without sacrificing decentralization. Built on a Bitcoin-like monetary framework but with optional shielded transactions, Zcash uses zero-knowledge cryptography to conceal balances and counterparties while still allowing the network to verify transactions. In other words, privacy isn’t theoretical — it already exists, and institutions are beginning to take it seriously.
As privacy increases, authentication becomes more important. In a world where AI can generate synthetic identities and automated agents at scale, financial systems need better ways to verify real people and institutions without exposing sensitive data—making privacy and authentication complementary requirements for crypto’s institutional phase.
What will the public notice first? Not blockchains themselves. Instead, people will see stablecoins embedded in familiar apps, tokenized assets inside brokerage accounts, and financial products that simply work faster and more globally than before. The technology fades into the background, as it always does once it succeeds.
If 2024 was about access and 2025 about adjustment, 2026 may be remembered as the year crypto crossed from experiment to infrastructure—not because prices moved, but because the system finally did.
You can find Grayscale research HERE.
Full Interview Here:
Thank you very much to our sponsors:
Truflation: BUY Truflation products/services and save 10% using code BOBDEW10. Learn about what prices are actually doing by going to https://truflation.com/marketplace/us-inflation-rate
Foundation: Protect your Bitcoin using the latest off-line technology with easy-to-use Passport. Their next product, Passport Prime will protect all passwords off-line with even-better technology. https://foundation.xyz/
River Financial: If not cold storage for your Bitcoin, I’d highly recommend River for buying and holding- River is engineered to protect your Bitcoin over the long run. Use this link for discounts: https://river.com/signup?r=T7GGAF7G
This was truly enlightening